
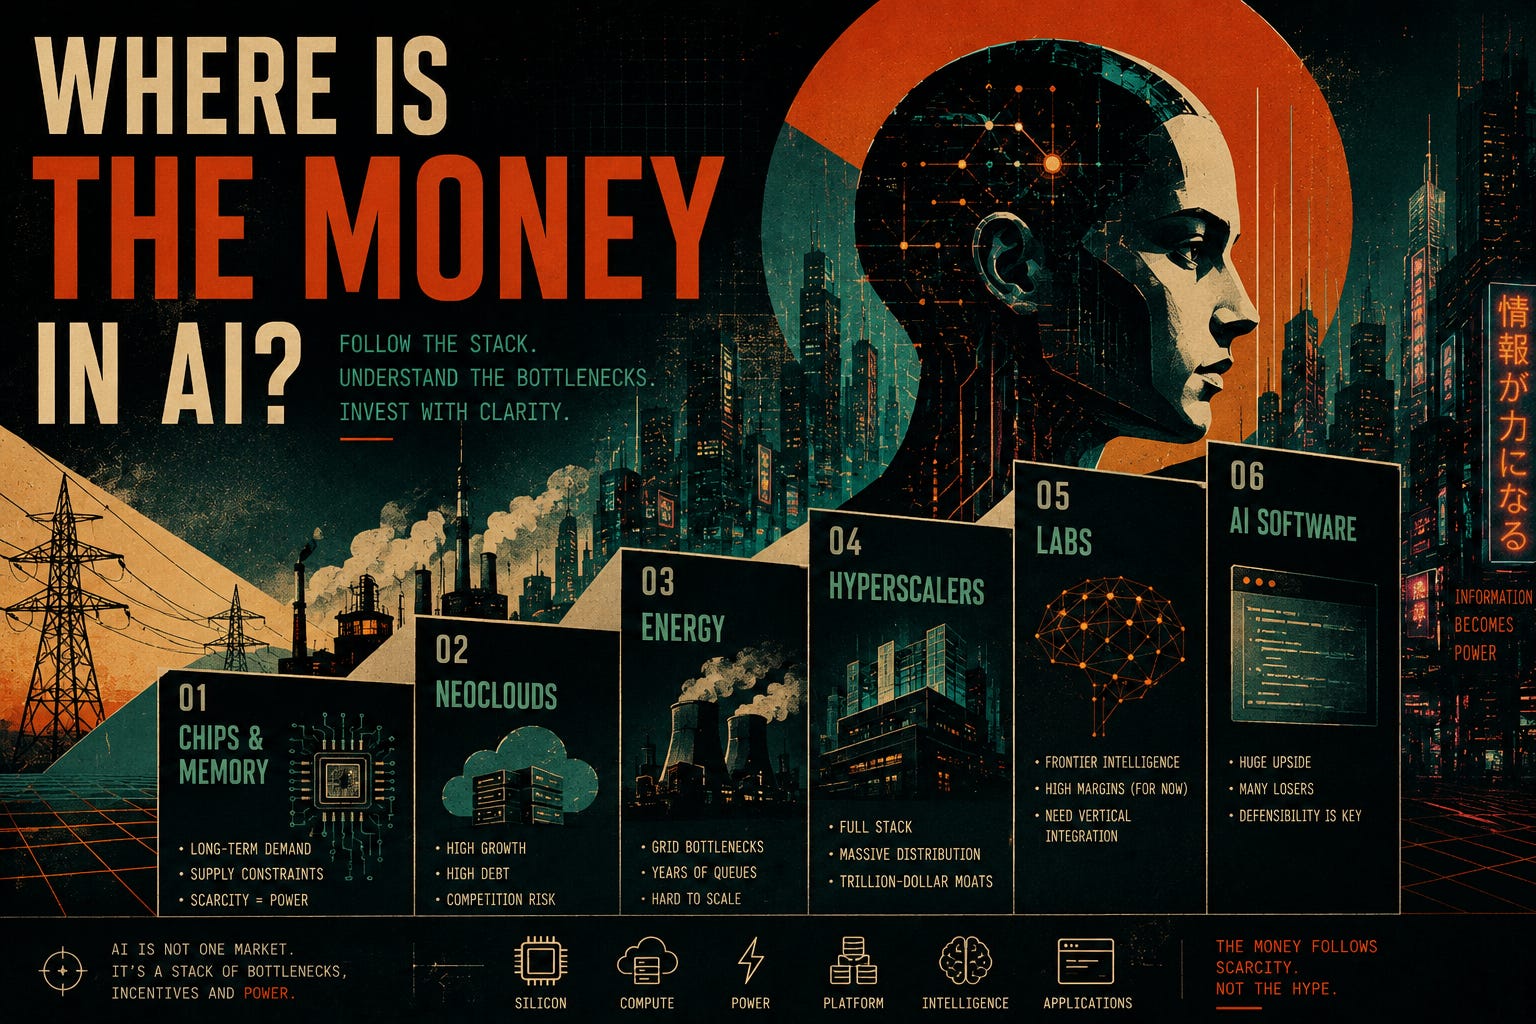
Everyone wants to invest in AI. Fair enough.
The slightly inconvenient question is:
What exactly are you investing in?
A memory manufacturer and an AI lab may both benefit from the same boom, but economically they have almost nothing in common.
One sells scarce physical capacity. Another sells intelligence whose marginal price may eventually approach commodity levels.
A neocloud finances GPUs with debt. A hyperscaler owns distribution, data centers, applications and sometimes its own silicon. An AI startup may currently have fantastic margins on something that becomes a feature inside Google Workspace six months later.
So I find “investing in AI” about as useful a category as “investing in electricity” would have been in 1900. The interesting question is where scarcity, pricing power and defensibility actually sit in the stack.
1. Chips and Memory: Wonderful Demand, Awkward Supply
Start with the obvious. AI needs an absurd amount of silicon.
GPUs get most of the attention, but the infrastructure behind them includes HBM, advanced packaging, foundries, networking silicon, lithography and a wonderfully complicated industrial chain where one missing component can delay billions of dollars of equipment.
Demand should remain enormous. But this isn’t purely a demand story. It’s a supply story.
Semiconductor capacity cannot be summoned by pressing Cmd+Enter. Fabs take years. Packaging capacity takes time. Lithography equipment takes time. And companies such as ASML sit at particularly interesting bottlenecks because everyone downstream can announce whatever glorious AI capex plan they like, but somebody still has to manufacture the machines required to manufacture the chips.
That’s attractive. But it also means valuation becomes extremely sensitive to capacity expectations.
If the market already assumes years of extraordinary demand, then “AI will need more chips” isn’t an investment thesis. Everyone knows. The thesis has to be about which bottleneck remains scarcer than the market expects.
2. Neoclouds: Selling Water During a Fire
Then we have CoreWeave, Nebius and the emerging AI cloud category. Right now, this is an excellent business environment.
Compute is scarce. Customers need enormous GPU clusters immediately. Hyperscalers cannot satisfy every request. So specialized providers can charge accordingly. The question is what happens when scarcity normalizes.
CoreWeave is a useful illustration of both sides of the trade. The company is growing spectacularly. Its Q2 2026 revenue reached $2.58 billion and its backlog exceeded $100 billion. It now expects to spend roughly $35–39 billion on capex this year. (Reuters) It also reported $25.1 billion of indebtedness as of March 31. (SEC)
That is a very different business from Google. Google can build infrastructure for its own products, train its own models, sell cloud capacity, redirect workloads internally and monetize AI through Search, Workspace, YouTube and advertising.
A neocloud mostly sells compute. If compute remains scarce, fantastic. If hyperscaler capacity catches up and GPU utilization falls, the moat becomes considerably less obvious. Neoclouds are currently selling water during a fire.
I’m less certain what the business looks like after someone installs more hydrants.
3. Energy: The Bottleneck We Created Ourselves
Power is even stranger. Unlike advanced semiconductors, electrons aren’t a new invention.
We know how to build power plants. We know how to build transmission. We know how transformers work. And yet grid interconnection has become one of the defining constraints on data-center expansion.
Recent research on AI data-center power economics makes exactly this point: interconnection queues increasingly determine where capacity can actually be built. (arXiv)
The semiconductor bottleneck is largely physics, engineering and industrial capacity. The electricity bottleneck is partly that, but also permitting, regulation, grid planning and bureaucracy. Which makes investing in “AI energy” surprisingly difficult.
Everyone can see demand coming. The problem is figuring out who actually captures the economics. The utility? The independent power producer? Natural gas? Nuclear? On-site generation? Grid equipment? Transmission?
My suspicion is that some of the more attractive opportunities aren’t electricity producers at all. They’re the companies selling whatever prevents the next gigawatt from being connected. More on that later.
4. The Hyperscalers: Probably the Winners, Unfortunately Already Enormous
Then we reach Google, Microsoft, Meta and the other giant platforms. Their advantage is almost embarrassingly comprehensive. They have infrastructure. They have capital. They have distribution. They have billions of users. They have proprietary data. They have applications. And increasingly, they have their own silicon.
Most importantly, they don’t necessarily need to sell AI. They sell outcomes already wrapped inside products.
A model lab sells you intelligence. Google can sell you Gmail, Search, Workspace, Cloud and YouTube with intelligence embedded inside them. Meta can turn better models directly into better advertising economics. Microsoft can distribute agents through an enterprise estate accumulated over decades.
This matters because distribution is becoming more valuable as production becomes cheaper. The problem for investors is obvious.
These aren’t undiscovered companies trading from a garage in Palo Alto. They are already worth trillions.
A company worth $3 trillion becoming worth $4 trillion is an excellent investment. It just isn’t 10x.
To get that kind of return from today’s giants, you need something approaching absolute dominance of the next economic cycle.
Possible? Sure. A modest assumption? Not particularly.
5. The Labs: Fantastic Business, Terrifying Economics
Now we reach the glamorous bit. Anthropic. OpenAI. The frontier labs. These companies are producing astonishing revenue growth.
Anthropic’s latest funding round valued it at $965 billion, with reported annualized revenue above $47 billion. (Anthropic)
OpenAI’s March financing valued it at $852 billion. (OpenAI)
Both have confidentially filed for IPOs, although neither has committed to a final public-listing timetable. (TechCrunch) The bull case is obvious. Intelligence becomes one of the largest markets in history, and these companies sell the best intelligence. The bear case is also obvious.
What happens to margins when intelligence becomes abundant?
Frontier inference can currently command excellent economics because capability is scarce. But labs compete aggressively. Open-source models improve. Inference gets cheaper. Customers become better at routing workloads toward the cheapest model capable of solving each task. And every lab faces the same unpleasant strategic treadmill:
You cannot simply stop spending on research because this year’s model is profitable. If your competitor produces something dramatically better next year, your beautiful margins become historically interesting. So the labs have to keep burning capital to defend the thing producing the margins.
This is why I think vertical integration matters enormously. Downward into chips, infrastructure and data centers. Or upward into applications, operating systems, devices and direct consumer relationships.
A pure model provider at a trillion-dollar valuation requires you to believe that model intelligence itself remains highly differentiated. I’m not convinced that is the safest assumption.
6. AI Software: Where Fortunes Will Be Made and Portfolios Murdered
Then comes AI software. This is simultaneously the most exciting and, to me, one of the most dangerous categories.
There will almost certainly be enormous AI-native companies. AI-native healthcare. AI-native education. AI-native entertainment. AI-native commerce. AI-native financial services. Perhaps entirely new categories we don’t have names for yet.
Some of these businesses will become extraordinarily valuable. But software itself is becoming dramatically cheaper to create. That’s the problem.
If your moat is: “We built this application,” a competitor increasingly responds: “Lovely. Give us the weekend.”
So defensibility has to move elsewhere. Distribution. Proprietary context. Accumulated user history. Regulatory position. Network effects. Physical infrastructure. Trust. Brand.
Unique data generated through actual usage. The winners could become the next Netflix or Amazon. But there may be two or three serious winners in a category while thousands of startups compete for the privilege.
That’s venture economics. Not necessarily a comfortable public-market investment thesis.
7. The Boring Stuff May Be the Interesting Stuff
Which brings me to the part of the AI stack I find increasingly fascinating. Transformers. Switchgear. Cooling. Power conversion. Grid interconnection equipment. Networking. Optical interconnects. Data-center construction. Maintenance. Backup systems. Industrial automation. Robots that inspect and maintain facilities. These aren’t as exciting as a model that can prove theorems or build software for nineteen days without human intervention.
Good. Excitement is expensive.
AI infrastructure is expanding faster than many physical supply chains can respond. And unlike software, you cannot fork a transformer on GitHub.
If demand increases fivefold while production capacity takes years to expand, you’ve found something worth studying.
Not necessarily buying at any price. But studying.
So Where Is the Money?
I don’t think there’s one answer. The AI economy is really a chain of different scarcity regimes.
Semiconductors: scarcity of manufacturing capacity.
Neoclouds: scarcity of immediately available compute.
Energy: scarcity of connected power.
Hyperscalers: scarcity of global distribution and integrated infrastructure.
Labs: scarcity of frontier intelligence, for as long as frontier intelligence remains scarce.
AI software: scarcity of defensible customer relationships and unique outcomes.
Physical infrastructure: scarcity of things that cannot be generated faster by making the model smarter.
And that’s probably the framework I’d use.
Don’t ask: “What benefits from AI?” Almost everything eventually will.
Ask: “What remains scarce if AI becomes 10x better and 10x cheaper?”
That’s where pricing power survives. And, rather inconveniently for an industry obsessed with intelligence, some of the best answers may turn out to be transformers, cooling pipes and people who know how to connect a data center to the grid.
Not quite as sexy as AGI. But markets have never paid extra for sexy once everyone notices it.